
The ICE BofA US High Yield Index was down 1.8% in 3Q26, including a 2.49% loss in the month of September, its worst monthly performance since September 2022. After 13 consecutive quarters of positive returns through Q4 2025, the index has posted negative returns in two of the first three quarters of 2026. Year-to-date gains stand at just 0.04%, raising the prospect of the high yield market’s first losing year since 2022.
Higher interest rates
Clearly, the abrupt and significant rise in interest rates has hurt: 10-year U.S. Treasury yields increased 85 bps in the third quarter alone, reaching a 20-year high of 5.29% at quarter end. Longer-duration BBs (those with a duration greater than four years) underperformed, declining 3.56%.
Heavy net primary issuance
The heavy supply of new high yield bonds - as well as the expectation of future issuance of AI-related debt – also played a factor in the market’s poor performance in September (which has continued into October).
The reversal in sentiment toward AI-related debt has unfolded over the past year. After being met with insatiable investor demand from late 2025 through mid-2026, some AI-related bonds started weakening in the summer. The bonds of CoreWeave, an AI cloud computing company with over $35bn in high yield bonds and loans and significant future funding needs, have performed especially poorly.
Investors are wary of heavy AI related issuance in the future and are being more selective. AI-related bonds already represent about 4% of the high yield index; some forecast that number to be as high as 7% to 10% in the next twelve months.
Issuance away from AI has been heavy as well. On September 30, 2026, Paramount Skydance priced approximately $52 billion in debt financing, including $11.4 billion in U.S. dollar high-yield bonds, to help fund its acquisition of Warner Bros. Discovery and refinance certain existing debt. Skydance, already a large issuer, will become the high yield market’s largest issuer on November 1 when it enters high yield indices with a weighting of approximately 1.9%.1
Figure 1: CoreWeave | 9.75% notes due 2031
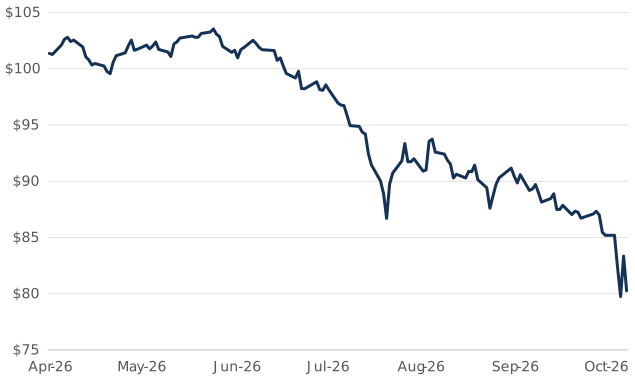
Data as of October 14, 2026
Source:Bloomberg
Poor CCC performance
In theory, CCCs are less sensitive to interest rates because of their wider spreads and lower duration, but they are more exposed to credit risk. Credit fundamentals, however, remain stable: the U.S. economy and corporate earnings are strong, high yield default rates are historically low, and the S&P 500 is near its all-time high.
Figure 2: CCC-BB spreads
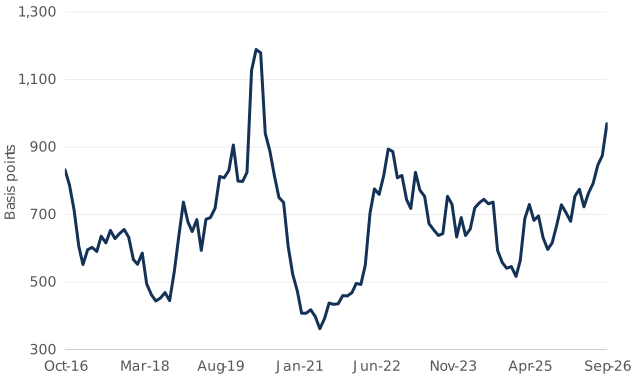
Data as of September 30, 2026
Source: ICE BofA
Are CCC spreads sending a signal? Some believe they are foreshadowing broader weakness in the credit markets, while others believe it may be a good time to buy credit risk.
They may not be saying much at all. For starters, CCC bonds are a smaller part of the high yield market than they used to be. CCC-rated bonds represented just 8% of the ICE BofA US High Yield Index as of September 30, compared to 11% just five years ago. Positively for the overall market, CCCs are also a smaller share of new issuance, averaging only 4% since 2022 compared to a longer-term average of roughly 9%.
The widening in CCC spreads this year has been driven largely by a handful of large capital structures, primarily Altice International and Altice USA, which together account for approximately 12% of the CCC segment. Excluding the two Altice issuers would reduce the spread of the CCC segment by approximately 200 bps, to 979 bps.
Spreads still trade at fairly tight levels. The spread to worst of the ICE BofA US High Yield Index is still only at 347 bps and at the lower end of the post GFC “non panic” range of 325 to 525 bps.
Yields, however, look more compelling on a quality adjusted basis. The current yield to worst of the ICE BofA US High Yield stands at 8.3%, higher than the median level of 6.7% since 2010, but more than 200 bps higher than the historical median level of 6.3% when accounting for the significantly higher shift in average quality of the market over the period.
Figure 3: CCC Segment OAS | ICE BofA US High Yield Index
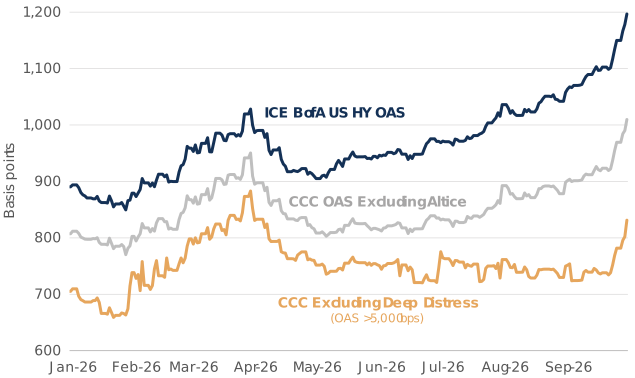
Data as of September 30, 2026
Source: ICE BofA US High Yield Index
1. Source: JP Morgan
2. ICE BofA
IMPORTANT DISCLOSURE
Availability of this document and products and services provided by MacKay Shields LLC may be limited by applicable laws and regulations in certain jurisdictions and this document is provided only for persons to whom this document and the products and services of MacKay Shields LLC may otherwise lawfully be issued or made available. None of the products and services provided by MacKay Shields LLC are offered to any person in any jurisdiction where such offering would be contrary to local law or regulation. It does not constitute investment advice and should not be construed as an offer to buy securities. The contents of this document have not been reviewed by any regulatory authority in any jurisdiction.
This material contains the opinions of the High Yield team of MacKay Shields LLC but not necessarily those of MacKay Shields LLC. The opinions expressed herein are subject to change without notice. This material is distributed for informational purposes only. Forecasts, estimates, and opinions contained herein should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information contained herein has been obtained from sources believed to be reliable, but not guaranteed. Any forward-looking statements speak only as of the date they are made and MacKay Shields assumes no duty and does not undertake to update forward-looking statements.
No part of this document may be reproduced in any form, or referred to in any other publication, without express written permission of MacKay Shields LLC. ©2026, MacKay Shields LLC. All Rights Reserved.
At the time of writing, MacKay Shields LLC maintains investments in the securities, issuers and/or companies cited herein. References to such securities, issuers and/or companies for educational and informational purposes only, and are intended to convey factual information and current market conditions. Such names are not intended, nor should they be construed as, a recommendation to buy and sell any individual security.
Information included herein should not be considered predicative of future transactions or commitments made by MacKay Shields LLC nor as an indication of current or future profitability. There is no assurance investment objectives will be met.
Past performance is not indicative of future results.
NOTE TO UK AND EUROPEAN UNION AUDIENCE
This document is intended only for the use of professional investors as defined in the Alternative Investment Fund Manager’s Directive and/or the UK Financial Conduct Authority’s Conduct of Business Sourcebook. To the extent this document has been issued in the United Kingdom, it has been issued by NYL Investments UK LLP, 200 Aldersgate Street, London UK EC1A 4HD, which is authorised and regulated by the UK Financial Conduct Authority. To the extent this document has been issued in the EEA, it has been issued by NYL Investments Europe Limited, 77 Sir John Rogerson's Quay, Block C Dublin D02 VK60 Ireland. NYL Investments Europe Limited is authorized and regulated by the Central Bank of Ireland (i) to act as an alternative investment fund manager of alternative investment funds under the Alternative Investment Fund Managers Directive (Directive 2011/61/EU) and (ii) to provide the services of individual portfolio management, investment advice and the receipt and transmission of orders as defined in Regulation 7(4) of the AIFMD Regulations to persons who meet the definition of “professional client” as set out in the MiFID Regulations. It has passported its license in additional countries in the EEA.
This document only describes capabilities of certain affiliates of New York Life Investment Management and/or MacKay Shields LLC. No such affiliates will accept subscriptions in any funds not admitted to marketing in your country or provide services to potential customers in your country, including discretionary asset management services, except where it is licensed to do so or can rely on an applicable exemption.
MacKay Shields LLC is a wholly owned subsidiary of New York Life Investment Management Holdings LLC, which is wholly owned by New York Life Insurance Company. "New York Life Investment Management" is both a service mark, and the common trade name of certain investment advisers affiliated with New York Life Insurance Company. Investments are not guaranteed by New York Life Insurance Company or New York Life Investment Management.
NOTE TO CANADIAN RECIPIENTS
The information in these materials is not an offer to sell securities or a solicitation of an offer to buy securities in any jurisdiction of Canada. In Canada, any offer or sale of securities or the provision of any advisory or investment fund manager services will be made only in accordance with applicable Canadian securities laws. More specifically, any offer or sale of securities will be made in accordance with applicable exemptions to dealer and investment fund manager registration requirements, as well as under an exemption from the requirement to file a prospectus, and any advice given on securities will be made in reliance on applicable exemptions to adviser registration requirements.
Information included herein should not be considered predicative of future transactions or commitments made by MacKay Shields LLC nor as an indication of current or future profitability. There is no assurance investment objectives will be met. Past performance is not indicative of future results.
NOTE TO JAPANESE RECIPIENTS
In Japan, this is issued by New York Life Investment Management Asia Limited (Financial Instruments Business Operator, Kanto Local Finance Bureau (FIBO) No. 2964, Member of the Investment Management Association of Japan and the Type 2 Financial Instruments Firms Association) for institutional investors only. As costs and/or fees to be borne by investors vary depending on circumstances such as products, services, investment period and market conditions, the total amount nor the calculation methods cannot be disclosed in advance. All investments involve risks, including market fluctuation and investors may lose the principal amount invested. Investors should obtain and read the prospectus and/or information set forth in Article 37-3 of the Financial Instruments and Exchange Act carefully before making investment decisions.
SOURCE INFORMATION:
“Bloomberg®”, “Bloomberg Indices®”, Bloomberg Fixed Income Indices, Bloomberg Equity Indices and all other Bloomberg indices referenced herein are service marks of Bloomberg Finance L.P. and its affiliates, including Bloomberg Index Services Limited (“BISL”), the administrator of the indices (collectively, “Bloomberg”) and have been licensed for use for certain purposes by MacKay Shields LLC (“MacKay Shields”). Bloomberg is not affiliated with MacKay Shields, and Bloomberg does not approve, endorse, review, or recommend MacKay Shields or any products, funds or services described herein. Bloomberg does not guarantee the timeliness, accurateness, or completeness of any data or information relating to MacKay Shields or any products, funds or services described herein.
All ICE Data indices referenced herein (each such index, the “Index”), are products of ICE data indices, LLC (“ICE Data”), and are used with permission. ICE® is a registered trademark of ICE Data or its affiliates, and BofA® is a registered trademark of Bank of America Corporation licensed by Bank of America Corporation and its affiliates (“BofA”) and may not be used without BofA’s prior written approval. ICE Data, its affiliates and their respective third party suppliers disclaim any and all warranties and representations, express and/or implied, including any warranties of merchantability or fitness for a particular purpose or use, including the indices, index data and any data included in, related to, or derived therefrom. Neither ICE Data, its affiliates nor their respective third party suppliers shall be subject to any damages or liability with respect to the adequacy, accuracy, timeliness or completeness of the indices or the index data or any component thereof, and the indices and index data and all components thereof are provided on an “as is” basis and your use is at your own risk. Inclusion of a security within an index is not a recommendation by ICE Data to buy, sell, or hold such security, nor is it considered to be investment advice. ICE Data, its affiliates and their respective third party suppliers do not sponsor, endorse, or recommend MacKay Shields LLC, or any of its products or services.
Subscribe to get MacKay Shields insights delivered to your inbox.
Related Thought Leadership